Slot Farm Tax Loophole: Bingo License Escape Route Revealed
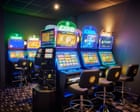
Slot Farm Tax Loophole Enables Business Rate Discounts
The slot farm tax loophole represents a significant regulatory gap that allows hundreds of adult gaming centres across England to maintain discounted business rates by retaining bingo hall licences. Despite recent government efforts to increase taxation on gambling operations, many high street gaming venues continue to exploit this administrative oversight, enabling them to avoid the full impact of new budget measures.
John Healey's recent budget announcement specifically targeted adult gaming centres (AGCs), increasing the duty on slot machine takings from 20% to 25%. However, this tax rise does not address the underlying issue of the slot farm tax loophole that allows gaming operators to claim preferential business rate treatment through bingo licensing designations.
Understanding Adult Gaming Centres and Bingo Licensing
Adult gaming centres, commonly referred to as "slot farms" due to their primary reliance on electronic gaming machines, operate in high street locations across England. These establishments differentiate themselves from traditional betting shops through their focus on arcade-style gaming rather than sports wagering. The critical issue emerges when these venues maintain active bingo licences despite minimal or non-existent bingo operations.
A bingo licence carries distinct business rate advantages that substantially reduce operational costs for gaming venues. By maintaining this licensing classification, hundreds of AGCs continue qualifying for business rate discounts originally designed to support traditional bingo halls. This regulatory mechanism creates a perverse incentive structure where gaming operators can legally minimize their tax obligations while operating primarily as slot machine venues.
Budget Tax Measures and the Remaining Gap
Chancellor John Healey's budget announcement represented a comprehensive approach to gambling taxation reform, specifically citing the need for "raising taxes on gambling to support good growth on every high street." The increase in slot machine duty from 20% to 25% constitutes a significant revenue-raising measure designed to generate additional government funds while potentially discouraging excessive gambling.
However, the budget measures focus exclusively on gambling duty rates rather than addressing business rate classification systems. This creates a scenario where even with higher gambling duties, venues exploiting the slot farm tax loophole benefit from reduced baseline business rates, partially offsetting the impact of increased duties on their operations.
The Scale of the Regulatory Gap
Reports indicate that hundreds of adult gaming centres maintain active bingo licences across England's high streets. These establishments collectively represent significant potential tax revenue currently being forfeited through business rate discounts justified by outdated licensing categories. The scope of this issue suggests systemic regulatory oversight rather than isolated compliance failures.
Local authorities issuing business rate assessments typically rely on licensing information provided by venues themselves. When an AGC lists a bingo licence as an active operating license, rating officers classify the property accordingly, regardless of actual operational focus. This administrative process enables venues to maintain preferential rates with minimal scrutiny or verification of legitimate bingo activities.
Closing the Loophole: Policy Implications
Addressing the slot farm tax loophole would require coordinated action between central government, local authorities, and regulatory bodies. Potential solutions include implementing stricter verification requirements for bingo licence holder status, establishing minimum operational thresholds for genuine bingo activities, or introducing business rate classifications that reflect actual venue operations rather than nominal licences.
The government faces a policy decision regarding whether to strengthen regulations during the current budget cycle or allow the existing loophole to persist. Closing this gap could generate substantial additional business rate revenue while creating more equitable tax treatment across the gaming sector.
Impact on High Street Businesses
The prevalence of adult gaming centres exploiting bingo licensing classifications raises questions about competitive fairness among high street retailers and service providers. Legitimate businesses operating under standard business rate assessments may face significantly higher tax burdens compared to gaming venues benefiting from licensing-based discounts. This creates market distortions that could influence high street development patterns and business viability.
Additionally, concentrated clustering of discounted-rate AGCs may contribute to changing high street dynamics, potentially displacing other retail uses and concentrating gambling opportunities in specific neighborhoods. The business rate discount structure inadvertently subsidizes this concentration pattern through preferential tax treatment.
Regulatory Framework Moving Forward
Treasury officials and local government representatives must determine whether current regulations provide adequate safeguards against the slot farm tax loophole or require substantive revision. The interaction between gambling duty increases and business rate classification systems reveals potential gaps in integrated policy design, suggesting that comprehensive gambling reform should address multiple revenue-raising mechanisms simultaneously.